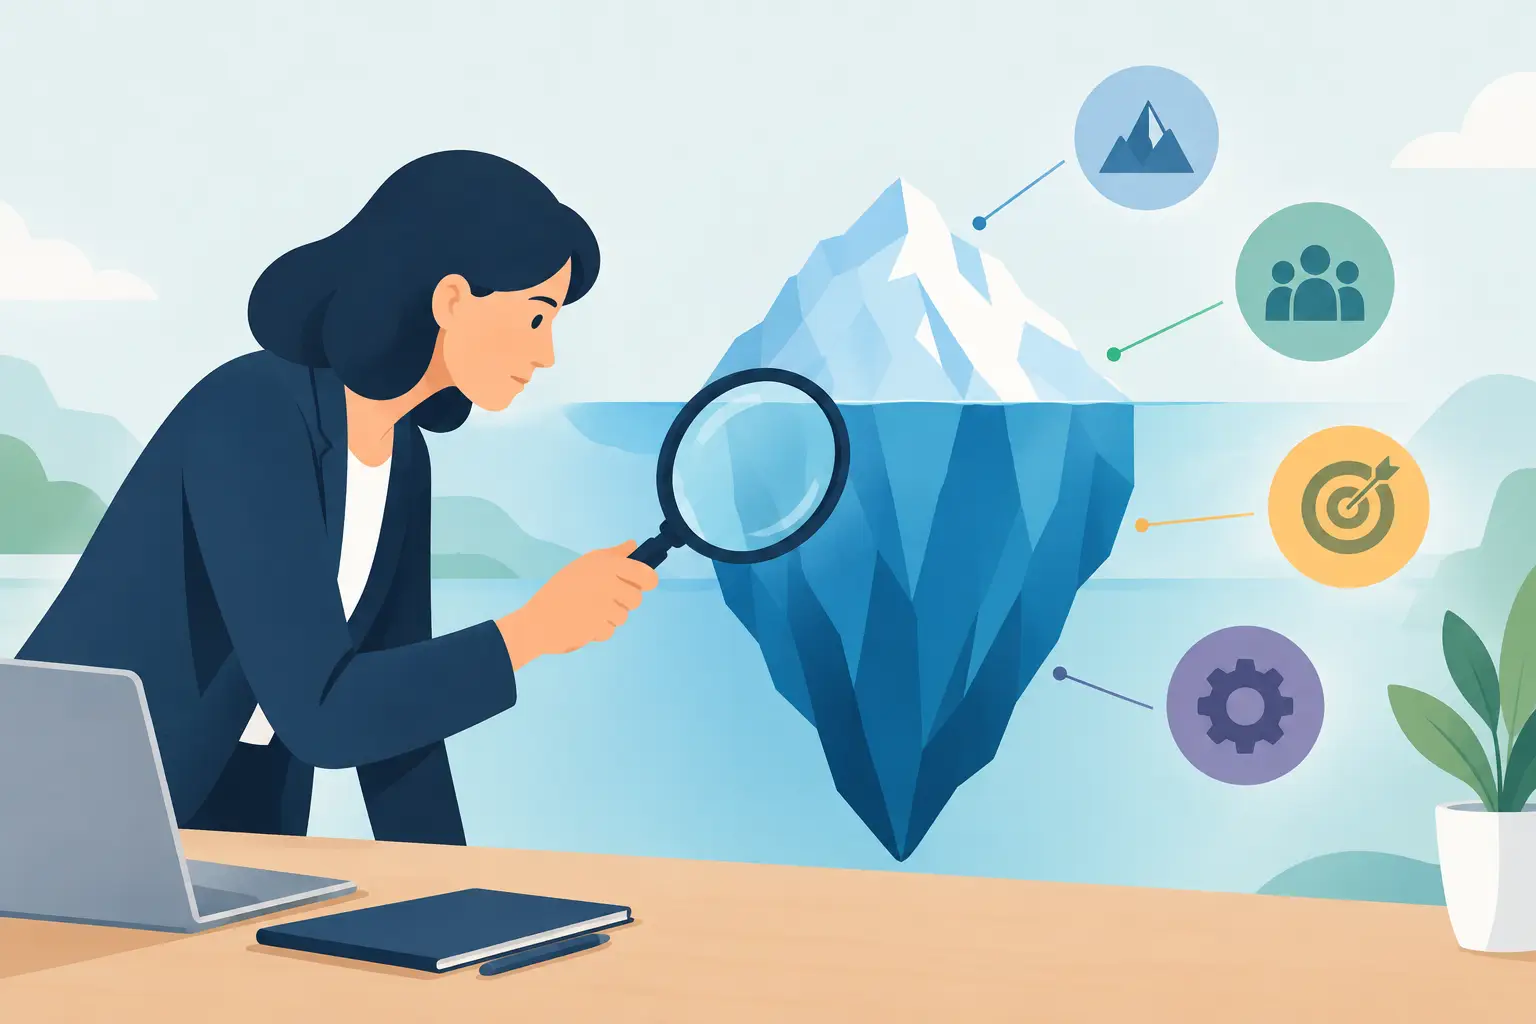
A strategy can be coherent, well modeled, and broadly supported while resting on premises no one has fully examined. Leaders may agree on the market opportunity, the investment case, or the transformation agenda without agreeing on what must be true for it to work. The discipline to surface hidden strategic assumptions is therefore not an academic exercise. It is a practical safeguard against committing capital, reputation, and organizational attention to an untested view of reality.
In high-pressure settings, assumptions tend to remain implicit for understandable reasons. The team has limited time. The sponsoring executive has already invested political capital. Directors do not want to appear obstructive when management is seeking momentum. Or the underlying belief feels so familiar that it is treated as fact.
The cost of this restraint is often paid later. A missed revenue plan, an integration that stalls, or an AI investment that produces activity without economic value is commonly described as an execution failure. Sometimes it is. But just as often, execution exposed an assumption that should have been challenged before the organization committed.
Why strategic assumptions stay hidden
Not all assumptions are equally visible. Some appear in financial models as explicit growth rates, pricing levels, or cost targets. These can be debated because they have been named. More consequential assumptions are often embedded in the framing of the decision itself.
A leadership team may assume that customers will value an expanded offer because adjacent customers have done so elsewhere. It may assume that an acquisition will create operating leverage because both businesses use similar language to describe their capabilities. It may assume that a new technology will reduce cost because the technical pilot performed well. Each statement may be plausible. None is self-validating.
Hidden assumptions persist because they sit at the intersection of authority, incentives, and identity. A founder may see a strategic move as the natural extension of the company’s original ambition. A management team may interpret dissent as lack of commitment. A board may hesitate to question a premise that management has presented with conviction and detail.
This is why better data alone does not solve the problem. Data can refine an assumption, but it cannot determine whether the team has framed the right question. Decision quality depends first on making the governing beliefs visible, then assigning them the appropriate level of scrutiny.
Surface hidden strategic assumptions before debate begins
The most useful moment to identify assumptions is before the room begins arguing about recommendations. Once participants have taken positions, challenge can become personal or political. Before that point, it can remain a shared effort to improve the decision.
A practical starting question is simple: what has to be true for this decision to produce the outcome we expect? The answer should not be limited to financial performance. It should cover customer behavior, competitive response, organizational capability, timing, regulatory conditions, capital availability, and the willingness of accountable leaders to make difficult trade-offs.
For example, a proposal to enter a new market may appear to depend on demand and distribution. Closer examination may reveal a more demanding set of assumptions: that the existing brand carries credibility in the new category, that local competitors will not change pricing, that leaders can recruit the required talent within a narrow window, and that the core business can absorb management distraction without consequence.
The point is not to produce an exhaustive inventory. Long assumption registers can create the appearance of rigor while leaving the central uncertainties untouched. The objective is to identify the few assumptions that are both material and fragile: beliefs that, if wrong, would change the decision, the scale of commitment, or the conditions attached to approval.
Separate facts, forecasts, and judgments
Senior teams benefit from a clear distinction between what is known, what is projected, and what is inferred. These categories are routinely blended in executive materials.
Facts are observable and verifiable: current customer concentration, signed contracts, cash on hand, demonstrated production capacity. Forecasts estimate a future state: expected retention, cost savings, adoption rates, or market growth. Judgments are interpretations about how people, markets, and institutions will behave under particular conditions.
A forecast may be precise without being reliable. A judgment may be reasonable without deserving to be treated as consensus. Labeling each statement appropriately changes the quality of the conversation. It allows directors and executives to challenge a judgment without disputing a fact, and to ask what evidence would justify confidence in a forecast.
Test the causal chain, not just the endpoint
Many strategic cases are persuasive at the endpoints. The opportunity is attractive. The projected value is substantial. What is often less clear is the causal chain between the two.
A board should ask how, specifically, the organization moves from investment to outcome. If a technology program is expected to improve margin, what operating decisions will change? Who has the authority to change them? What adoption behavior is required? When will management know whether the benefit is material rather than anecdotal?
This approach exposes dependency. A projected outcome may rely on commercial adoption, process redesign, data quality, talent availability, and leadership follow-through occurring in sequence. If one dependency fails, the investment may still have value, but the original business case no longer holds. That distinction should shape both approval and oversight.
Challenge assumptions without weakening accountability
Constructive challenge is not a vote of no confidence in management. It is part of responsible governance. The quality of challenge depends on whether it clarifies ownership or diffuses it.
The most effective questions are specific and decision-relevant. What evidence would cause us to revise this view? Which assumption is carrying the largest share of the value case? What alternative explanation best fits the available evidence? If the expected result does not appear within six months, what decision will we make differently?
These questions are stronger than generalized requests for more analysis. They require the sponsoring executive to state the conditions of confidence and the conditions of reconsideration. They also help the board distinguish between uncertainty that can be managed and uncertainty that should change the commitment itself.
There is a trade-off. Excessive challenge can delay action and encourage defensive analysis. Insufficient challenge turns speed into a substitute for judgment. The appropriate level of scrutiny depends on reversibility. A decision that can be tested through a limited pilot deserves a different process from a large acquisition, a major capital allocation, or a strategic shift that will consume senior leadership attention for years.
Turn assumptions into decision conditions
Once a material assumption has been identified, it should lead to an explicit decision condition. This is where disciplined framing becomes operational.
A decision condition might require independent validation of customer willingness to pay before a full commercial rollout. It might set a threshold for integration readiness before a transaction closes. It might establish a staged investment, with further funding tied to evidence of usage, margin improvement, or risk reduction. In each case, the organization is not seeking certainty. It is defining what must be demonstrated before exposure increases.
Decision conditions also improve accountability after approval. Instead of revisiting a strategy only after results disappoint, leadership can monitor whether the assumptions that justified the decision are holding. If they are not, the response becomes a matter of pre-agreed governance rather than a late, politically charged debate.
This is particularly valuable for boards and investment committees. Oversight is more useful when it tracks the integrity of the original decision logic, not merely the delivery of milestones. A project can meet milestones and still fail because its central assumptions were false. Conversely, a project can miss an early milestone while preserving its strategic rationale if the essential assumptions remain intact.
Make dissent usable
The final discipline is cultural, but it is not soft. A leadership team needs a way to register informed dissent without treating it as disloyalty or forcing artificial unanimity.
One effective practice is to ask the most informed skeptic to articulate the strongest case against the proposal, then ask the sponsor to respond directly. Another is to record material dissent alongside the decision, including the evidence that would later prove the dissent well founded. This does not diminish the authority of the final decision-maker. It makes the basis for ownership clearer.
Averi Advisory often sees that the strongest leadership teams are not those that eliminate disagreement quickly. They are those that can identify where disagreement sits: on facts, forecasts, values, risk tolerance, or accountability. Once the source is clear, the group can decide whether more evidence is needed, whether the decision should be staged, or whether the responsible executive should make the call despite unresolved uncertainty.
The next consequential decision does not require a larger presentation or a longer forecast. It requires a more candid answer to a harder question: which belief are we relying on most, and what will we do if it proves wrong?